Lifestyle Inflation
1
What It Is
Lifestyle inflation occurs when spending rises alongside income, leaving individuals no more financially secure despite earning more. It is not a moral failure but a predictable behavioral pattern that emerges from convenience, social pressure, and the gradual normalization of incremental upgrades. Each small improvement feels earned, yet collectively they absorb raises and bonuses before those gains can strengthen long-term security.
2
Why It Happens
The causes are structural as much as personal. Peer groups shift as careers advance, bringing new social expectations and consumption norms. Digital commerce removes friction from purchasing, making upgrades feel effortless. Most significantly, people rarely pre-decide how future income will be allocated, so each raise triggers a fresh round of ad hoc decisions rather than deliberate planning.
The Hidden Cost
The damage is not immediate bankruptcy but the slow erosion of optionality. Money that could fund transitions, withstand setbacks, or support meaningful choices instead becomes embedded in fixed commitments — larger mortgages, premium subscriptions, and lifestyle standards that are easy to enter and difficult to exit. The result is a career that looks successful on the surface but feels precarious underneath.
Breaking the Cycle
Intervention requires more than budgeting willpower. Effective approaches make spending visible through regular review, introduce gentle friction to impulsive upgrades, and rehearse future scenarios before income changes arrive. The goal is not deprivation but deliberation: enjoying the fruits of labor while ensuring those fruits are chosen consciously rather than absorbed automatically.
The Velmariqora Approach to Spending Discipline
A framework built for how people actually live
Velmariqora's methodology treats lifestyle inflation as a behavioral challenge rather than a mathematical one. The approach recognizes that willpower is a finite resource, that social pressures are real and persistent, and that the solution lies in reshaping the environment of decision-making rather than demanding heroic self-denial.
Make It Visible
Regular structured reviews illuminate where money actually flows, surfacing patterns that routine obscures.
Add Gentle Friction
Small delays and categorization prompts reduce impulsive upgrades without requiring constant vigilance.
Rehearse Futures
Scenario planning makes abstract income changes feel concrete, enabling calmer decisions when they arrive.
Build Feedback Loops
Lightweight monitoring systems catch drift early, before small shifts accumulate into large commitments.
How Lifestyle Inflation Creeps In
The gradual erosion of financial margin
The process begins imperceptibly. A promotion brings a slightly better apartment. A new social circle introduces different restaurants. A convenience service saves fifteen minutes daily. Each decision is minor, each upgrade feels earned, and the cumulative effect is invisible until the gap between income and security has widened dramatically.
The mechanism is not greed but adaptation. Humans normalize new circumstances with remarkable speed, a trait that serves well in adversity but works against financial stability when applied to rising consumption. Yesterday's luxury becomes today's baseline, and the hedonic treadmill accelerates without conscious consent.
Income increases trigger immediate spending adjustments
Social circles reshape consumption expectations
Convenience services embed as non-negotiable expenses
The Danger
Lifestyle inflation is invisible until it is not
Real Scenarios of Lifestyle Inflation
The First Promotion
A junior analyst receives her first significant raise and immediately upgrades her apartment, her transportation, and her wardrobe. Within eighteen months, the additional income is fully absorbed by higher fixed costs.
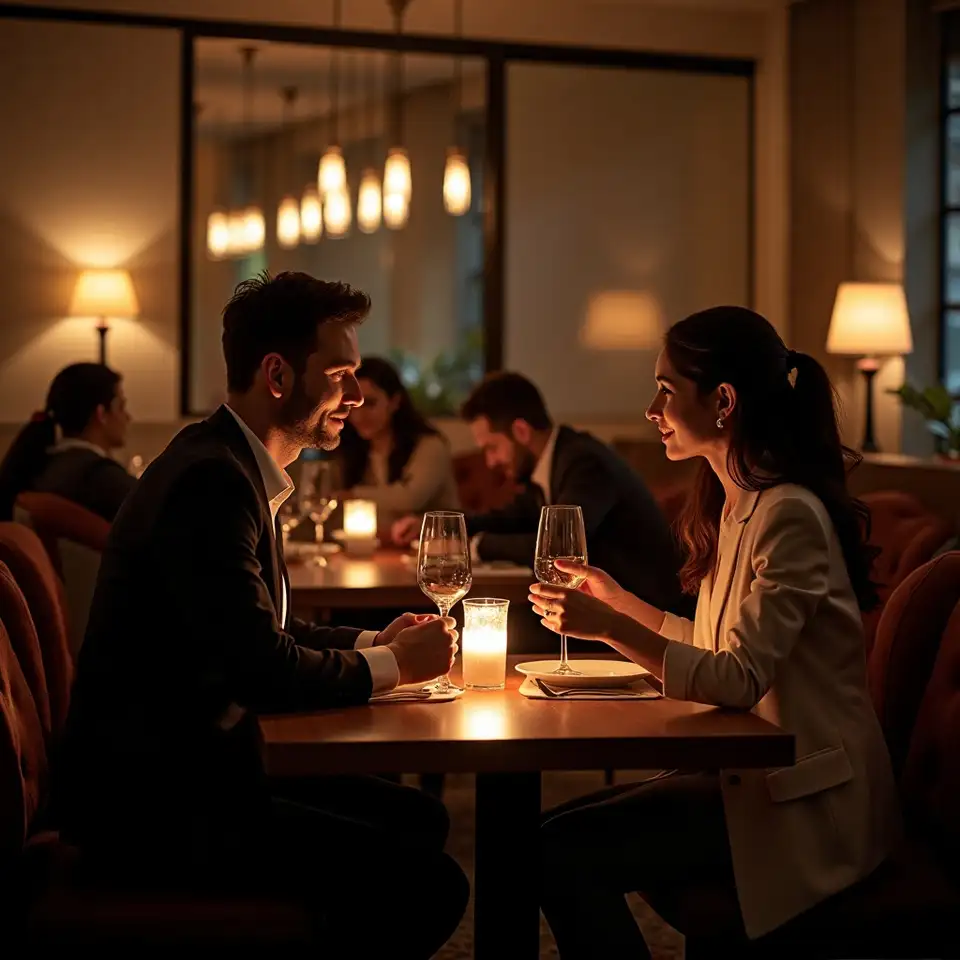
The Social Circle Shift
A marketing manager enters a new peer group where weekend trips and premium
dining are standard. What began as occasional participation becomes expected
routine, and discretionary spending resets permanently upward.
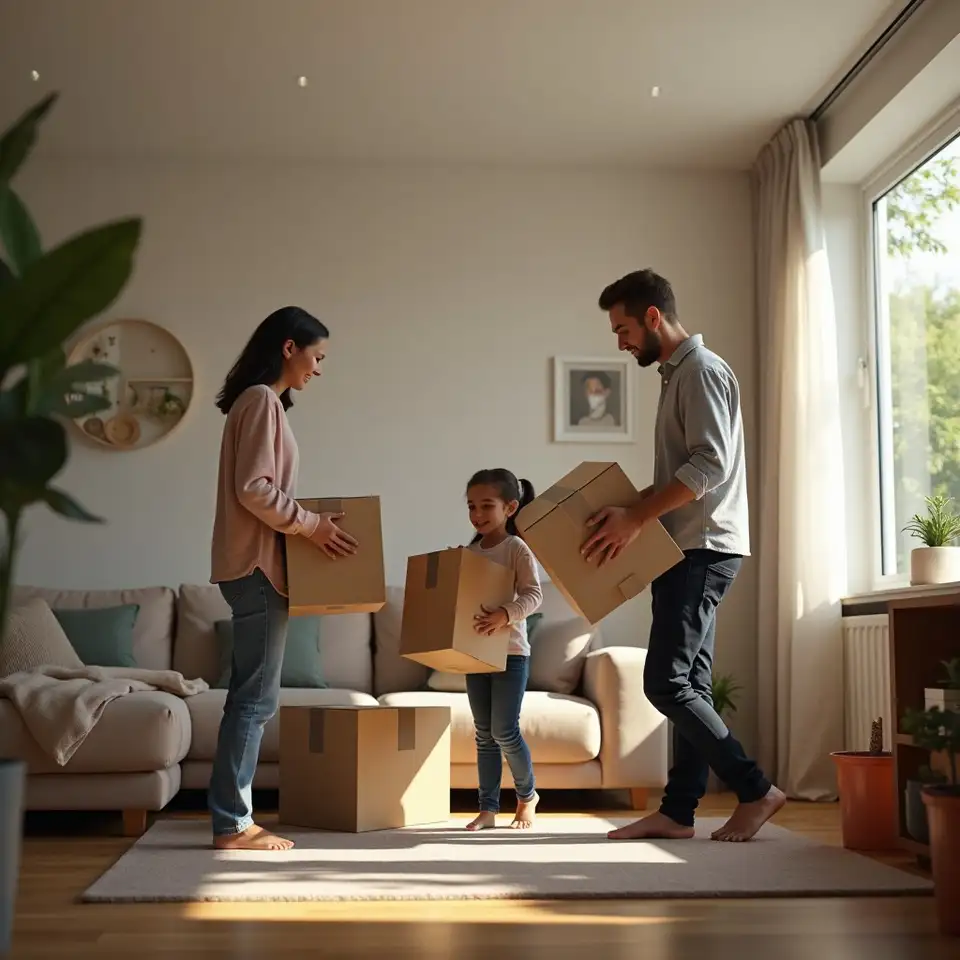
The Family Expansion
A dual-income couple has children and relocates to a larger home in a premium school district. The mortgage, services, and activities that follow commit them to maintaining two high incomes indefinitely.
The Executive Transition
A director-level promotion brings business-class travel, executive dining, and
wardrobe expectations. These initially employer-subsidized habits gradually
become personal standards that outlast the role.
The Late-Career Realization
A senior professional recognizes that decades of incremental upgrades have
created a lifestyle that cannot be sustained without peak earnings, leaving
limited flexibility for reduced hours or career changes.
Understanding Lifestyle Inflation
Velmariqora's educational framework helps individuals recognize the early signals of lifestyle inflation and build sustainable responses before patterns harden into fixed commitments.
Core Learning Areas
- Recognizing Early Warning Signals: The framework teaches participants to identify the subtle indicators that spending is outpacing intention: expanding subscription lists, increasing reliance on convenience services, and the gradual replacement of functional possessions with premium alternatives. These signals appear long before financial distress becomes visible.
- Mapping Social and Professional Pressures: Income growth rarely occurs in isolation. Promotions bring new peer groups, travel expectations, and consumption norms. The methodology helps individuals distinguish which expenditures reflect genuine personal values and which emerge from unexamined social pressure or professional performance signals.
- Building Scenario-Based Planning Skills: Rather than reacting to income changes after they occur, participants learn to rehearse multiple financial futures in advance. This practice reduces the decision fatigue that accompanies raises, bonuses, and career transitions, enabling calmer allocation choices under pressure.
- Establishing Sustainable Monitoring Systems: Awareness without structure fades quickly. The framework includes lightweight review practices that maintain visibility over spending patterns without requiring exhaustive tracking or constant self-denial. These systems catch drift early, when intervention remains easy.
Session Goals
By engaging with this framework, individuals develop the capacity to observe their own spending patterns with clarity, distinguish genuine preferences from social pressures, and maintain deliberate control over lifestyle expansion throughout their earning years.
What Makes This Different
Unlike traditional financial education that focuses on accumulation and restraint, this approach acknowledges that careers advance and lifestyles naturally evolve. The goal is not to prevent all spending growth but to ensure that expansion happens by choice rather than default, preserving optionality and security along the way.
The Psychology Behind Lifestyle Inflation
Lifestyle inflation is not fundamentally about money. It is about adaptation, social
belonging, and the human tendency to normalize new circumstances with remarkable speed.
When income rises, the mind does not automatically recalculate what is necessary versus
what is merely available. Instead, it absorbs the new resources into existing patterns,
expanding comfort without expanding security. The psychological mechanisms at work are
well-documented. Hedonic adaptation ensures that the satisfaction from any upgrade fades
quickly, leaving a hunger for the next improvement. Social comparison operates
constantly, often below conscious awareness, as individuals calibrate their consumption
against visible peers. Present bias favors immediate gratification over distant
security, making the tangible pleasure of today's upgrade feel more real than the
abstract benefit of tomorrow's flexibility. Velmariqora's framework addresses these
mechanisms directly rather than pretending they can be overcome through willpower alone.
By making spending visible, introducing structured delays before upgrades, and
rehearsing future scenarios in vivid detail, the methodology works with human psychology
rather than against it. The result is not a life of deprivation but one of deliberate
choice — where each expenditure reflects genuine preference rather than automatic drift,
and where career success translates into meaningful security rather than an endless
cycle of incremental consumption.
Key Indicators of Lifestyle Inflation
Recognizing the patterns before they become fixed commitments is the first step toward deliberate control. These indicators often appear gradually, each reasonable in isolation, collectively transformative in their impact on long-term financial flexibility.
Expanding Subscription Footprint
What begins as a single streaming service multiplies into a portfolio of recurring charges for entertainment, fitness, meal delivery, and productivity tools. Each subscription feels minor individually, yet their combined monthly outflow often exceeds what the individual would consciously allocate to discretionary spending.
Convenience Service Dependence
Services that began as occasional luxuries — ride shares, grocery delivery, housekeeping — gradually become perceived necessities. The time saved is real but rarely redirected toward income-generating or security-building activities, and the cost compounds silently.
Incremental Possession Upgrades
Functional items are replaced with premium versions not because the original failed
but because the improved version became socially visible or personally tempting.
Phones, vehicles, and wardrobes are common domains where this pattern accelerates.
Fixed Cost Expansion
Housing, transportation, and insurance costs rise with income in ways that are difficult to reverse. Larger apartments, financed vehicles, and comprehensive coverage create commitments that persist even if income later stalls or priorities shift.